

13 November 2026
From Proof of Concept to Proof of Market
Five years of building carbon removal and the road to bankability: what lenders, developers and buyers need from the next five years.

Issue #78 of the Carbonaires Monthly Newsletter previews COP31 in Antalya: the politics, the market rules and the demand signals to watch. No big new carbon market rules are on the table, but demand for high-integrity credits and removals is arriving from governments, compliance markets and corporate standards.
Five years of building carbon removal and the road to bankability: what lenders, developers and buyers need from the next five years.
Issue #78 of the Carbonaires Monthly Newsletter previews COP31 in Antalya: the politics, the market rules and the demand signals to watch. No big new carbon market rules are on the table, but demand for high-integrity credits and removals is arriving from governments, compliance markets and corporate standards.
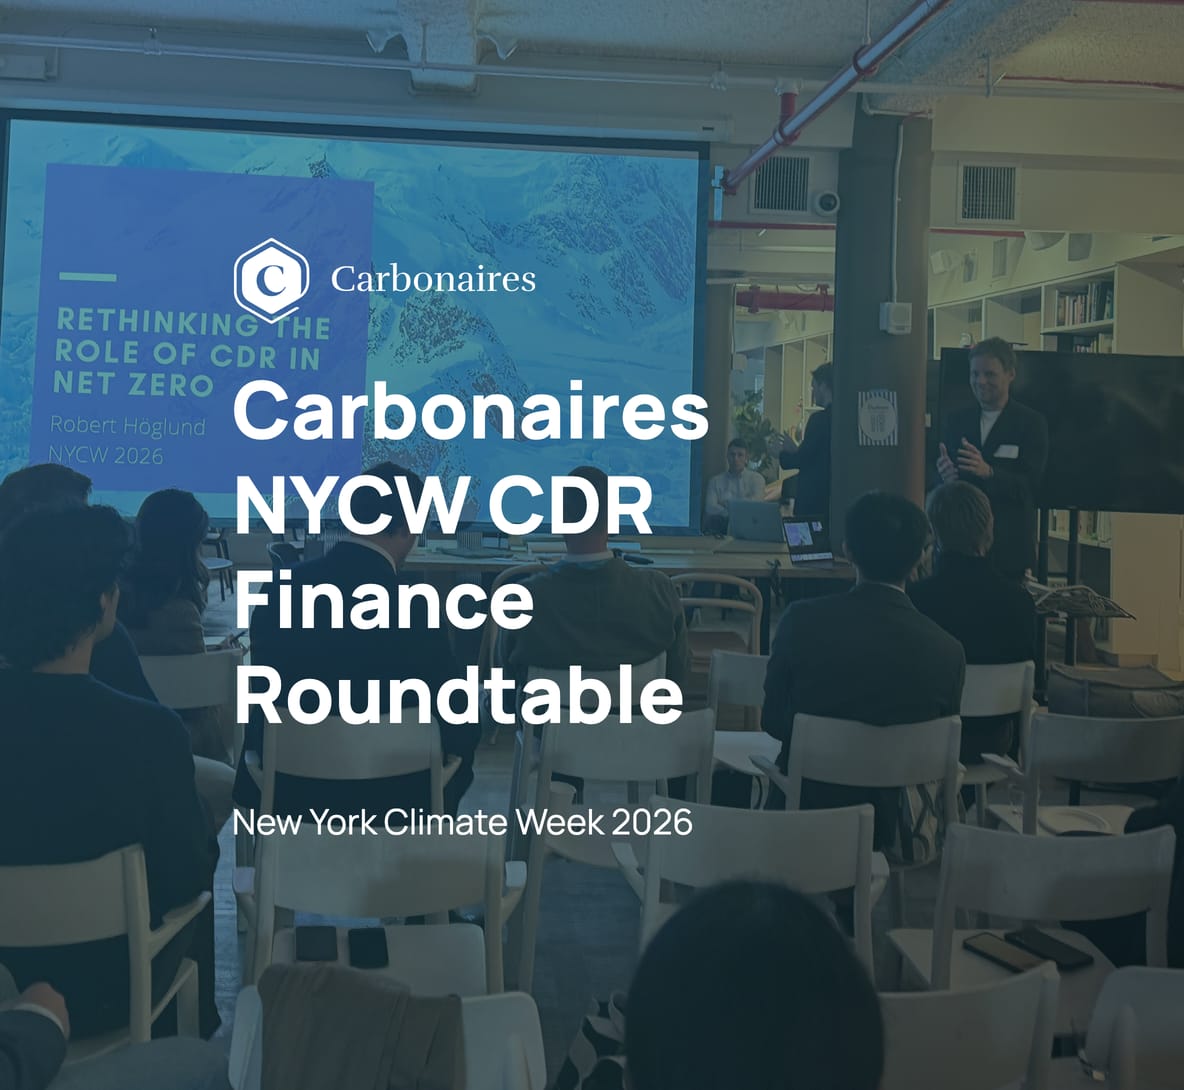
Carbon removal projects are securing buyers and attracting investment, but bringing more debt into the market depends on contracts that provide certainty over revenue and allocate risks in a way projects can sustain. At our closed-door CDR Finance Roundtable during Climate Week NYC, investors, lenders, insurers, traders and market builders heard briefings from Carbonaires, Philip Lee and Milkywire, then discussed contracts and risk allocation, bringing more debt into CDR, and how to value uncontracted supply.
Issue #77 of the Carbonaires Monthly Newsletter makes the case for carbon markets as climate finance ahead of COP31. Building on our contribution to the Turkish Presidency’s Climate Implementation Bridge at the Istanbul Climate Finance Summit, it sets out how carbon revenue and long-term offtake agreements make mitigation projects investable, how Article 6 can turn national climate plans into financeable project pipelines and fund additional domestic action, and why recognition of carbon finance now needs to lead to funded buyer commitments.
Issue #75 of the Carbonaires Monthly Newsletter examines the European Commission’s proposal to revise the EU Emissions Trading System, published on 17 July: a 250 million allowance facility ring-fenced to purchase BioCCS and DACCS removals through to 2040, a further 260 million allowances for high-integrity international credits, and a slower cap decline. Set alongside SBTi Version 2 and the draft ISO 14060 standard, it points to carbon removal demand that can be modelled, dated and priced, and to a creditworthy government offtake that begins to solve the tenor problem holding back debt financing.
Superpollutants — methane, HFCs, nitrous oxide and other non-CO2 climate pollutants — are responsible for roughly half of the warming experienced today, and abating them is now seen as the fastest available lever on temperature this decade. With Google making its first move into the market and superpollutant categories the first through the ICVCM gate, CCP-labelled credits rated among the market’s highest quality are now available at a fraction of removal prices.
Shoosmiths, one of the UK’s leading law firms, has entered into a five-year pre-purchase forward offtake agreement with Carbonaires, securing a long-term supply of durable biochar carbon removals from HUSK to support its zero net operational emissions. Rather than buying spot credits, Shoosmiths locked in supply, volume and price over five years — a strategic, long-term approach to high-integrity carbon removal.
Issue #74 of the Carbonaires Monthly Newsletter covers two developments shaping carbon markets in June 2026: our analysis of the SBTi Corporate Net-Zero Standard Version 2 — a measured step in the right direction that recognises companies’ ongoing emissions through a new Ongoing Emissions Responsibility framework, but stops short of the near-term incentive needed to mobilise the corporate removal demand the market requires to scale — and a review of London Climate Action Week 2026, where the market’s centre of gravity shifted decisively from ambition to execution.
Issue #73 of the Carbonaires Monthly Newsletter covers three developments shaping carbon markets in May 2026: why portfolio construction is the buyer’s first line of defence as deliveries slip behind contracts, the policy push to unlock carbon removal demand through buyers’ clubs and corporate claims clarity, and the EU’s draft rules opening CBAM to Article 6 credits and what this signals for compliance-driven credit demand.
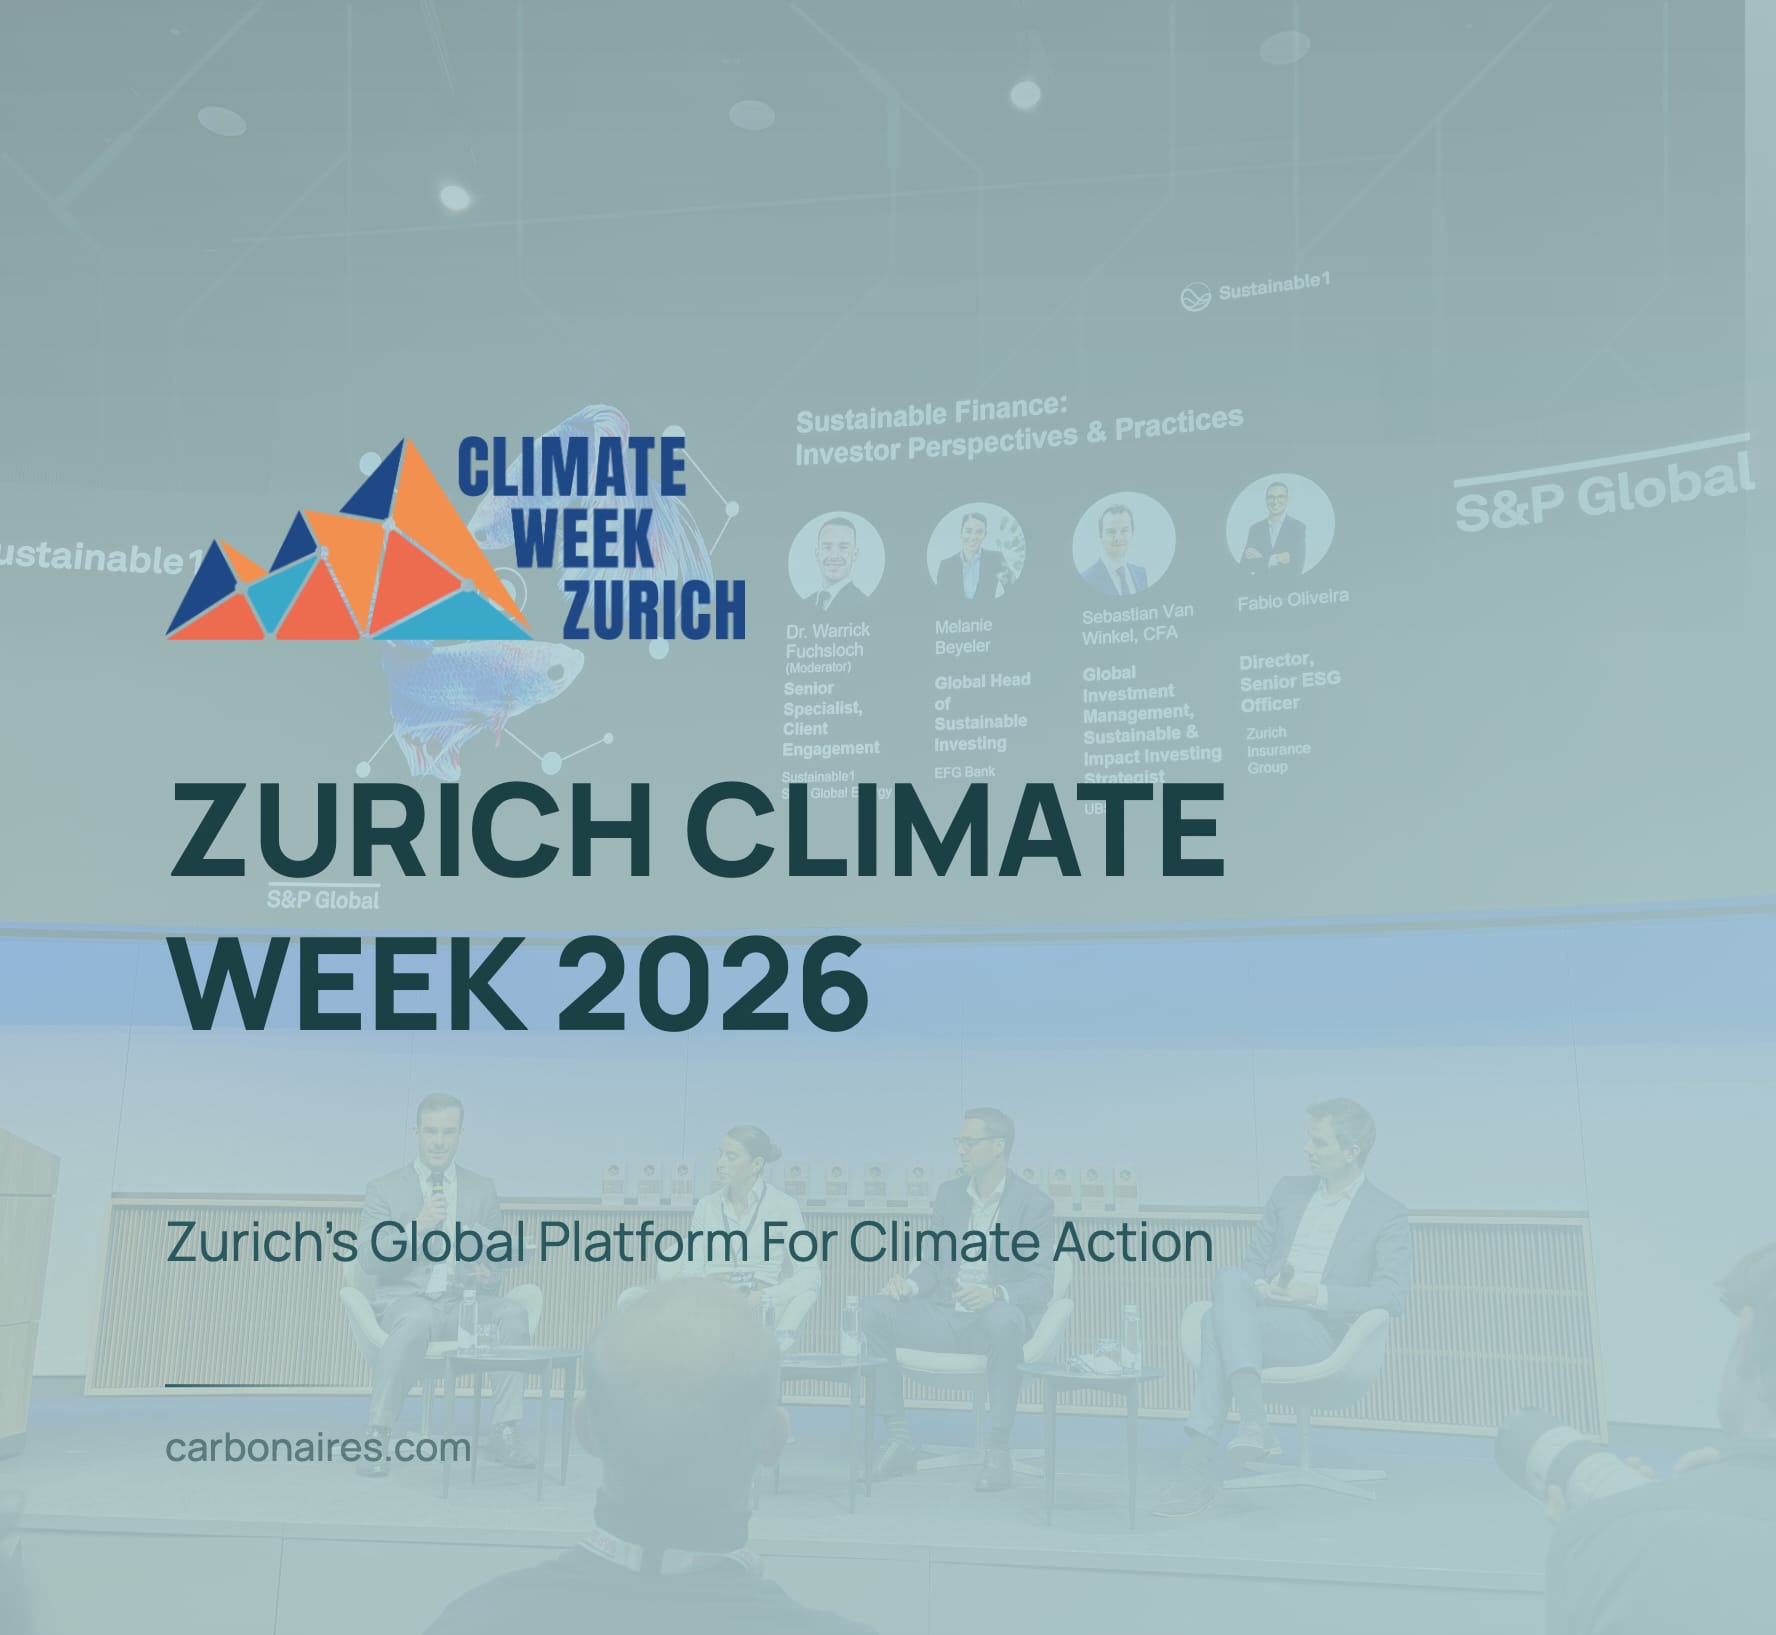
Key takeaways from Zurich Climate Week 2026 (5–7 May 2026). Across the S&P Global Sustainability Yearbook launch, UBS Innovating for Nature, the Green Fintech Network CDR session and UBS Energy Transition, the message was consistent: the market has moved past intention, and execution is now the measure of credibility.
Key takeaways from the Argus Europe Carbon Conference 2026 in Nice (11–13 May 2026). With the EU ETS under review, CBAM in its definitive phase, the CRCF approaching first issuances, and CORSIA implementation faltering, the European carbon market is at a decision point — and the missing piece is demand-side policy, not supply.
Reflections from Energy Tech Summit 2026 at the Euskalduna Conference Centre in Bilbao (15–16 April 2026). 1,400+ senior attendees from KKR, BlackRock, Shell, Microsoft, NVIDIA, Iberdrola and more set out how the energy infrastructure build-out has fully absorbed the carbon question — and what that means for high-integrity carbon removal demand, the “last 20%” problem and compute-linked credit models.
Newsletter
We will keep you updated on the latest news in green finance, if you subscribe to our newsletter. You can consent to receive our newsletter here.
By clicking "Subscribe" you agree to receive newsletters about any updates, events, news, special offers, surveys, and promotions via email in accordance with the Privacy Policy. We may also use your email address to tailor our advertising.
You may always withdraw your consent by clicking on the unsubscribe link in any newsletter you have received from us.
